The Banking theme just spiked 12 spots on the Scouter board, driven by a surge in investment banking fees. But those advisory fees aren't just coming from mega-cap tech buyouts—they are being minted in the regional bank sector, where a brutal consolidation wave is forcing sub-$10 billion lenders to either scale up or sell out. We are tracking three Financials setups this week where M&A speculation, institutional jockeying, and credit quality reviews converge.
CFFN: The Balance Sheet Diligence
You cannot sell a bank—or buy one—if your loan book is toxic. For CFFN, the M&A narrative hinges heavily on asset quality, making its upcoming credit risk review on Thursday, October 15, 2026, a critical clearing event. The bank currently carries an elevated loan-to-deposit ratio and rising non-performing assets, which act as a heavy anchor on strategic flexibility.
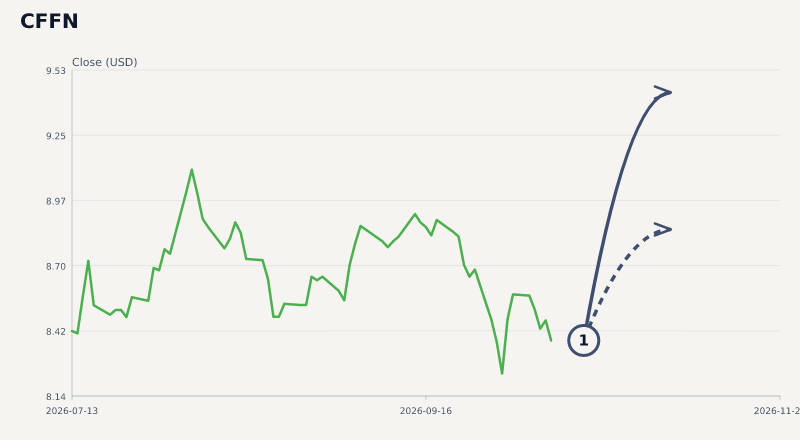
Historical outcomes for regional bank credit reviews show a balanced mix of bullish and bearish resolutions. If the review confirms stable capital adequacy without requiring massive reserve builds, Scouter's modeled scenario suggests a re-rating toward a $9.43 target by the time the window resolves on Saturday, October 31, 2026. Conversely, any forced provisioning could drag the stock down toward a modeled bear floor of $8.85 as acquirers walk away.
BVFL: The 13F Takeout Premium
Regional bank consolidation relies on institutional sponsors to force the issue. For BVFL, the catalyst kicks off on Thursday, October 15, 2026, as fall 13F filings land alongside peak M&A chatter. The bank’s small market cap, healthy capital levels, and robust deposit base make it a textbook takeout candidate for a larger regional player looking to scale its footprint.
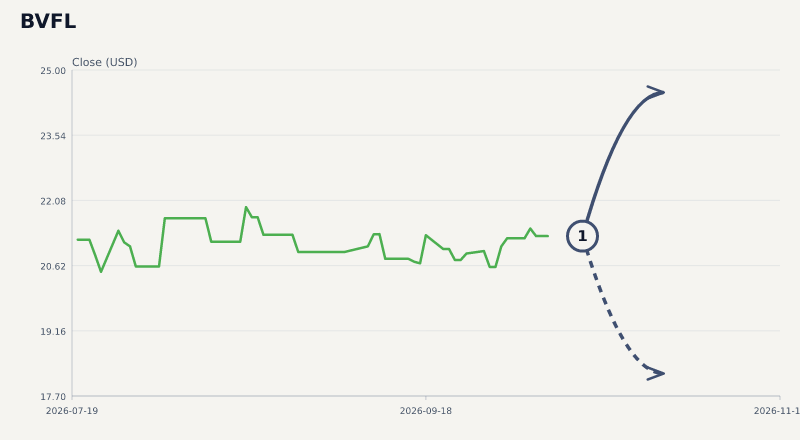
Empirical patterns show that M&A-related catalysts in financials skew positively, with definitive deals often driving a median run-up of 6% to 7%. If credible takeover rumors or visible activist accumulation materialize by the Thursday, October 29, 2026 resolution date, our analysis flags a modeled bull target of $24.50 as investors price in a control premium. But M&A speculation is a double-edged sword; if the filings show institutional distribution rather than accumulation, the stock risks a sharp unwind toward an $18.20 bear floor.
SMBC: Sizing the Acquirer Advantage
Not every regional bank is prey; the ones with strong liquidity are using the current environment to play predator. SMBC faces a sector consolidation test starting Thursday, October 15, 2026, as the market evaluates its positioning in the M&A food chain. The bank is currently riding deregulatory tailwinds that are expected to ease capital requirements, giving it the exact balance sheet flexibility needed to absorb smaller peers.
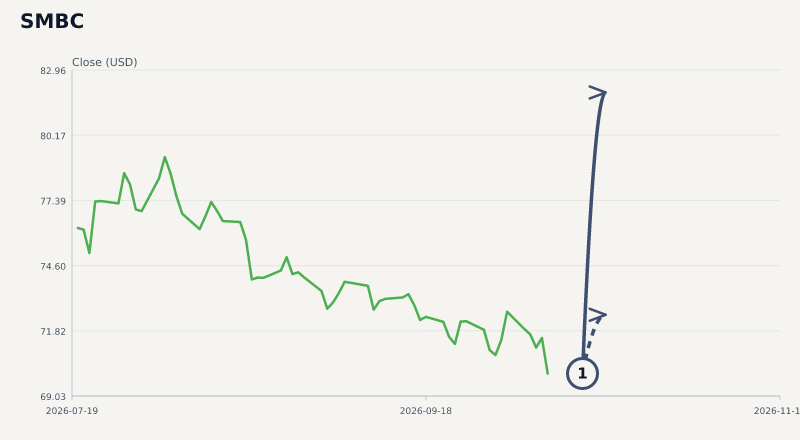
Starting from a $78.50 base, learned patterns indicate that M&A activity yields a strong 66.7% bull outcome rate for banks in this tier. Speculation around strategic consolidation justifies an asymmetric upside target of $82.00 by the Monday, October 19, 2026 resolution date. If SMBC fails to participate in the wave or signals a retreat from acquisitions, the market will likely re-rate its standalone value toward a $72.50 fallback.
Structuring the Regional Endgame
The investment banking fee surge is a direct reflection of structural pressure on smaller financial institutions. With net interest margins compressed by lingering rate-cycle effects, scale is no longer just an advantage—it is a survival requirement. Banks that can successfully navigate credit reviews and attract institutional capital will dictate the terms of the next cycle.
For investors, the setups landing this week offer a real-time stress test of the M&A thesis. The market is aggressively sorting the regional banking landscape into acquirers, targets, and structural orphans. Assessing these near-term catalysts helps clarify which side of the advisory fee exchange these banks will ultimately sit on.