The structural shift from expensive inpatient hospital beds to high-efficiency ambulatory care is a massive reallocation of capital. As the aging population demands more frequent, lower-acuity interventions, institutional cash flow simply follows the volume. This week, we get a fundamental stress test across that entire value chain.
Here is what Scouter’s Aging Population Drives Growth in Ambulatory Care theme—which just rocketed 27 spots to the top of our board—is modeling for the week of November 2.
Concentra and the CMS Rate Reality
Regulatory clarity is the absolute bedrock of healthcare pricing models. On Monday, November 2, 2026, the CMS Medicare Physician Fee Schedule Final Rule drops, testing whether CON can secure sustainable reimbursement rates. The previous rule squeezed Concentra’s margins due to an unfavorable mix, making this week's release a critical test of operational adaptability.
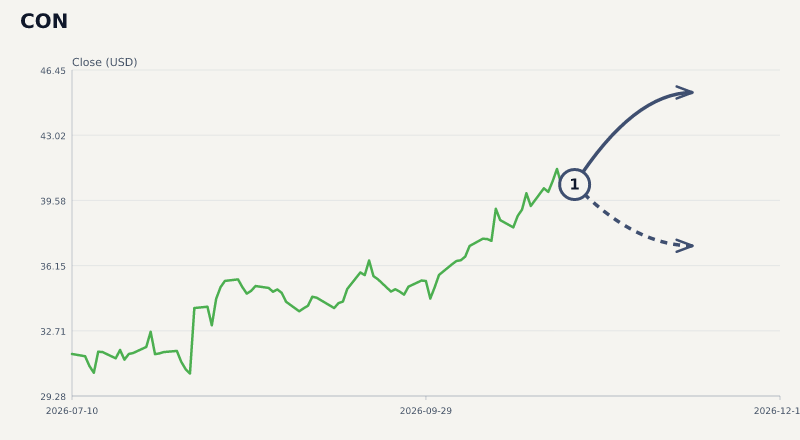
Scouter's modeled scenario framework suggests a favorable rate adaptation could drive shares toward a $45.27 bull target, with the outcome window resolving by Sunday, November 29, 2026. Conversely, if the finalized rates compress revenue realization again, the resulting multiple contraction points to a $37.19 bear floor.
Carter Bankshares and the NIM Tightrope
Regional lenders serve as the engine room for this demographic shift, financing the real estate and equipment footprint for new localized clinics. When CARE reports its Q3 2026 Earnings Release on Thursday, November 5, 2026, the market will rigorously scrutinize net interest margin (NIM) and forward credit quality. Recent trading underscores how sensitive the shares remain to credit provisioning and deposit costs rather than headline balance sheet growth.
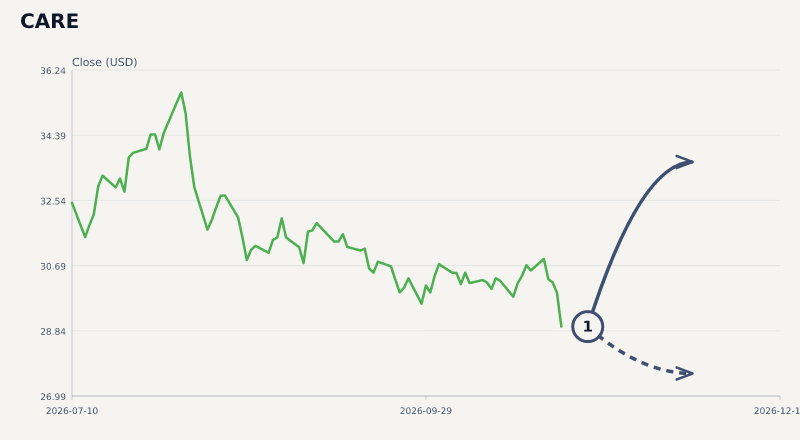
Recent macroeconomic data suggests rate pressure will persist, leaving little room for error on funding costs. If management delivers constructive commentary on forward NIM trends, Scouter models a re-rating toward $33.63, resolving Sunday, November 29, 2026. If margin compression accelerates instead, downside risk concentrates near the $27.63 level.
Cigna and the Specialty Pharmacy Bar
The payer and pharmacy benefit layers are where the actual cost of this outpatient migration gets managed and ultimately monetized. CI steps to the podium for its Q3 2026 Earnings Release on Thursday, November 5, 2026. Analysts are intensely focused on Evernorth’s specialty pharmacy growth and the persistent threat of elevated medical cost trends across the commercial book.
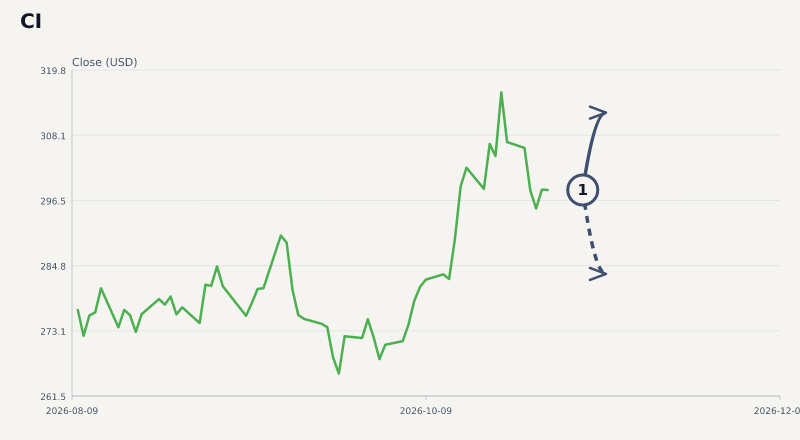
Cigna currently trades at an 11.5x P/E, a staggering discount to the 28x industry average that sets a uniquely low clearance bar. Backed by solid revenue growth and a history of earnings beats, Scouter models a bull resolution toward $312.19 by Monday, November 9, 2026. However, if elevated medical utilization overshadows top-line growth, the stock could retreat to $283.32.
Capitalizing the Outpatient Era
The capital flowing into the ambulatory care migration is structural, but the profit margins are highly conditional. The setups landing this week illustrate the immediate friction of that transition, highlighting federal rate resets, the cost of localized capital, and specialty pharmacy utilization.
Investors who simply buy the demographic trend risk getting chopped up by these specific transmission mechanisms. Mapping out the regulatory and fundamental checkpoints helps you assess who actually captures the economic value as care permanently leaves the hospital.