The demographic shift toward an aging population is steadily forcing healthcare out of expensive inpatient wards and into ambulatory settings. The "Aging Population Drives Growth in Ambulatory Care" theme just rocketed 34 spots to rank number one on our Trend Scores board. The structural demand is undeniable, but the transition costs for providers and equipment suppliers remain a brutal gauntlet.
This week, three of the top ideas in the ambulatory care basket face critical tests of their unit economics. Market pricing will strip away the demographic narrative to see who is actually converting the volume into free cash flow.
Stryker and the Outpatient Capex Cycle
Hospitals are frantically buying capital equipment to handle the outpatient surgical surge, and SYK is positioned at the center of that spending flow. The medical device manufacturer drops its Q3 2026 Earnings Release & Procedural Volume Update on Friday, October 30, 2026. After logging a robust 9% organic growth rate in the second quarter, investors are looking for sustained backlog realization.
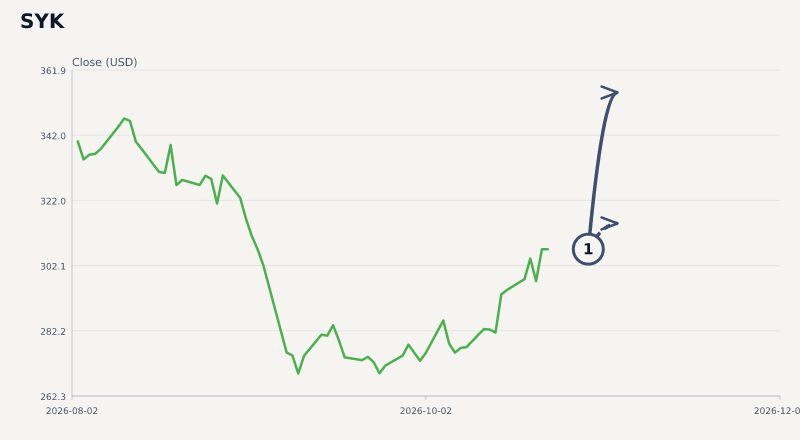
With shares trading near a premium 21.8x EV/EBITDA multiple, the technical runway requires a flawless beat-and-raise to hit our modeled $355.00 bull target. However, if management flags supply chain bottlenecks or tightening hospital budgets, the stock's valuation offers little cushion. Any margin pressure would quickly trigger the $315.00 fallback path.
Community Health and the Margin Gauntlet
While suppliers sell the picks and shovels, facility operators like CYH carry the heavy debt load of the transition. The hospital operator reports its Q3 2026 Earnings Release on Thursday, October 29, 2026, confronting acute pressure from CMS reimbursement constraints. Their previous print highlighted the drag of lower inpatient volumes on aggregate revenue.
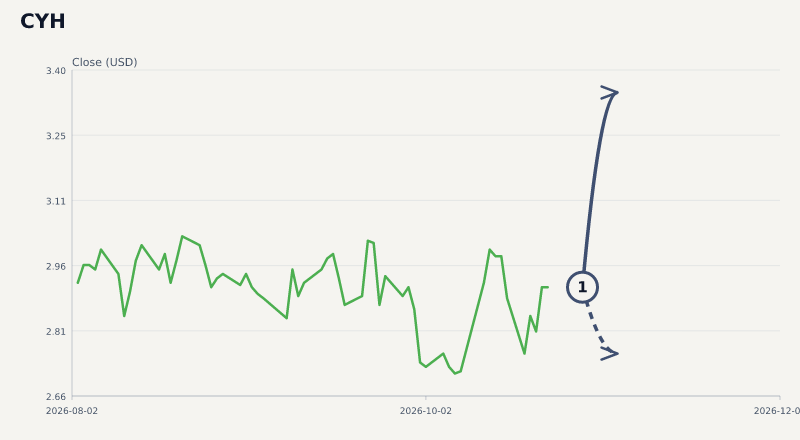
This quarter acts as a crucial referendum on management's ability to defend margins while shifting the case mix. If guidance resets favorably, historical volatility suggests a potential 12% squeeze toward the modeled $3.35 target. Conversely, failing to show structural expense discipline risks a slide toward the $2.76 floor.
Fortrea Tests the Backlog Conversion
Clinical research and trial execution for age-related therapeutics require flawless operational discipline. FTRE issues its Q3 2026 Earnings Release on Thursday, October 29, 2026, stepping into the spotlight after a punishing second quarter where severe margin compression hammered the stock. The market needs proof that the company can actually convert its backlog into cash.
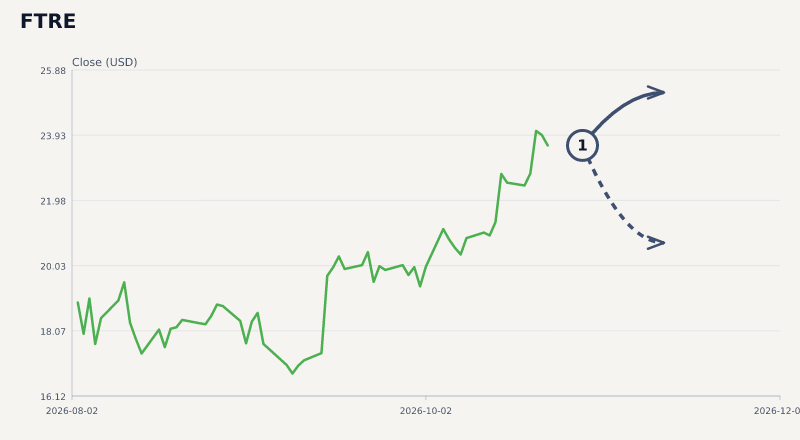
Guidance and margin stabilization will drive price resolution far more than the headline revenue number. A credible path to adjusted profitability could spark a recovery to our modeled $25.21 bull target. If they lack visibility or report further margin decay, shares risk drifting back to the $20.71 baseline.
Pacing the Healthcare Migration
The long-term shift toward outpatient and ambulatory care is structurally inevitable, but the profit pools along the way are not evenly distributed. Equipment providers with pricing power operate in a fundamentally different reality than leveraged facility operators battling CMS rate caps.
This week's earnings slate will clarify which operators are successfully capturing the demographic tailwind and which are simply being crushed by the transition costs. Investors should watch the margin commentary closely, as top-line growth means nothing if the unit economics are bleeding out.